


Moreover, if the subsidiary incurs losses that exceed the carrying amount of the investment, the parent firm should recognize these losses, doubtlessly leading to a unfavorable carrying amount. The Fee Method is applied when the father or mother firm has little to no affect over the subsidiary, usually owning lower than 20% of the voting inventory. In this scenario, the investment is recorded at its unique purchase value and isn’t adjusted for the subsidiary’s subsequent earnings or losses.
Understanding how to account for investments in subsidiaries is crucial for businesses aiming to present accurate financial statements. This apply not solely ensures compliance with regulatory requirements but in addition offers a transparent image of the company’s monetary health and efficiency. Precisely recording investments in subsidiaries is crucial for maintaining clear and compliant financial statements.
- This implies that the funding account is eradicated and one hundred pc of every asset and legal responsibility of the subsidiary is reported inside the father or mother company’s balance sheet on a line-by-line basis.
- The consolidation method also requires the mother or father firm to disclose details about non-controlling interests (minority shareholders), offering transparency in how income and losses are allotted.
- This contains adjustments for objects such as revaluations of assets, modifications in accounting insurance policies, or other complete revenue items.
- The mother or father company would report $580,000 as a debit (an increase) to the Funding in Subsidiary Asset Account and a credit to the Funding Income Account.
Proudly Owning a subsidiary can considerably influence varied monetary ratios, altering how analysts view a mother or father company’s monetary well being. The inclusion of a subsidiary’s assets and liabilities in the parent company’s stability sheet can change the debt-to-equity ratio and return on equity (ROE). These shifts can present a more complete view of how the father or mother firm leverages its resources. For the fairness technique, show the funding as a non-current asset with periodic adjustments for the parent’s share of the subsidiary’s income or losses.
However, there isn’t any impression to our total belongings on the steadiness sheet as one asset decreases (credit of funding in subsidiary), whereas another asset increases (debit of cash). This journal entry will increase both complete assets on the balance sheet and total revenues on the revenue statement because of a rise in investment in subsidiary. Moreover, constant losses from a subsidiary may lead the parent investment in subsidiary accounting company to reconsider its investment strategy.
Common Evaluation And Testing For Impairment


Nevertheless, when a parent company initially acquires a portion of a subsidiary, it debits Funding in Subsidiary by the acquisition quantity after which credits cash by the acquisition quantity. Nonetheless, it’s necessary to notice that the fairness methodology often just isn’t acceptable for audited subsidiary financial statements. If your organization owns a subsidiary or is a subsidiary of another company, the accounting processes are totally different from conventional, single-entity accounting.
Accounting For Insurance Coverage Proceeds: Monetary And Tax Results

If the investor intends to revenue https://www.bookkeeping-reviews.com/ from near-term (generally within than 12 months of preliminary investment) value movements, they are classified as either Trading Securities. If the investor doesn’t intend to commerce the securities within the near-term, they’re thought of Out There for Sale. Alternatively, the investment could be called simply Investment in Affiliate(s), especially when no available market prices for the securities are available. On January 1, as we acquired 80% of share possession within the firm XZY, it grew to become our subsidiary company afterward. This is as a end result of once we obtain the cash dividend from the subsidiary, it signifies that the investee’s net price or fairness is decreased as nicely.
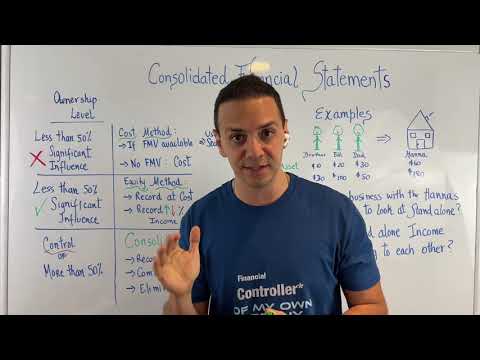
Other elements, such as native laws, the subsidiary’s monetary well being, and operational independence, may also affect the accounting strategy. For occasion, some jurisdictions might require specific disclosures or accounting treatments for partially owned subsidiaries, further complicating the method. The consolidated method is normally most popular over the fairness methodology if the share the father or mother company owns is on the upper facet (more than 50%, or if it controls the subsidiary). Conversely, the mother or father could also be bigger than some or all of its subsidiaries (if it has more than one), as the connection is defined by management of ownership shares, not the number of employees.

This entails regularly evaluating the carrying amounts of the subsidiary’s property and liabilities to ensure they replicate current circumstances. Changes could additionally be necessary to account for changes in market situations, operational performance, or other related elements. This ongoing reassessment helps maintain the accuracy and reliability of the consolidated financial statements.
The mother or father company’s share of the subsidiary’s profits is already included in the consolidated internet income, so recognizing the dividend separately would lead to double-counting. By eliminating these intercompany dividends, the consolidated monetary statements current a extra correct picture of the group’s total financial efficiency and position. The consolidation technique is utilized when a mother or father company workout routines management over a subsidiary, typically through ownership of more than 50% of the voting stock. This technique entails combining the monetary statements of the father or mother and subsidiary into a single set of financial statements, presenting them as one economic entity. The process begins with the aggregation of the subsidiary’s property, liabilities, revenues, and bills with these of the parent company. This comprehensive method offers a holistic view of the monetary position and efficiency of the entire group.
What’s The Journal Entry For Investment In Subsidiary?
The company as a bunch will need to consolidate the financial statements using the “consolidation method” by which the investment in subsidiary account might be removed. The acquisition price is not merely the worth paid for the shares but also encompasses other elements such as authorized charges, due diligence costs, and any other expenses instantly linked to the acquisition course of. These additional costs are capitalized and included in the initial measurement of the funding. This comprehensive method ensures that the recorded value of the investment reflects the entire economic outlay incurred by the mother or father firm. Consolidation includes eliminating intercompany transactions, corresponding to loans, revenues, or expenses between the father or mother and subsidiary.


